S&P500 Daily Action Areas & Price Targets 14/10/26
S&P500 Daily Action Areas & Price Targets 14/10/26
***QUOTING ES1!(Z CONTRACT LEVLES) FOR CASH US500 EQUIVALENT LEVELS, SUBTRACT POINT DIFFERENCE***
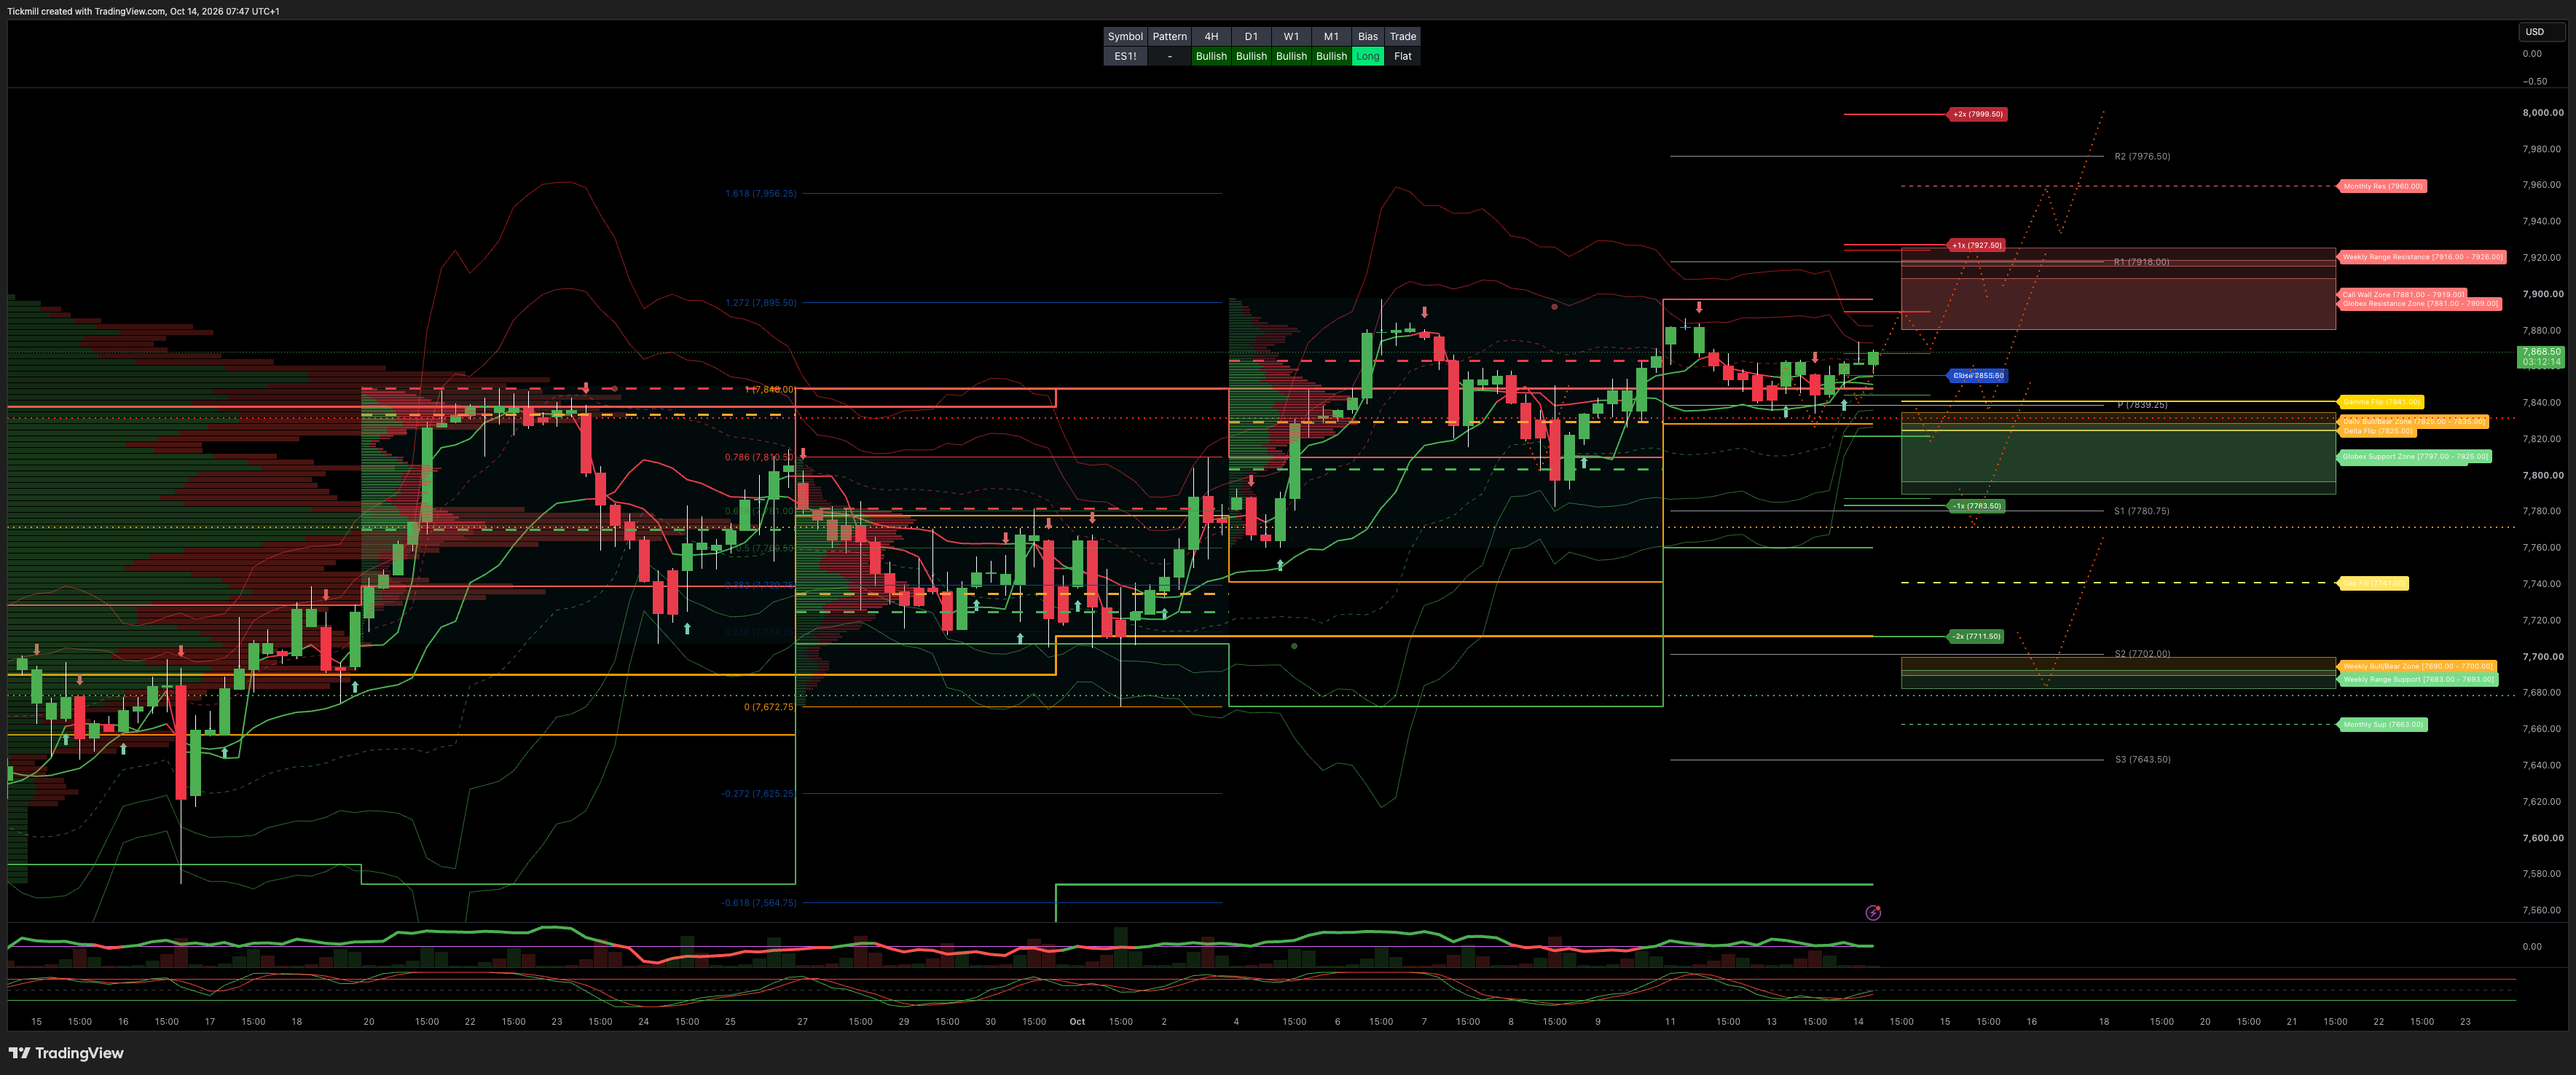
MONTHLY-WEEKLY& DAILY LEVELS
MONTHLY BULL BEAR ZONE 7440/7400
MONTHLY RANGE RES 7960 SUP 7663
WEEKLY BULL BEAR ZONE 7700/7690
WEEKLY RANGE RES 7926/16 SUP 7683/93
DAILY BULL BEAR ZONE 7835/25
GLOBEX RANGE SUP 7825/7797 RES 7881/7909
GAMMA FLIP 7841
DELTA FLIP 7825
CALL WALLS 7919/7881
PUT WALLS 7790/7829
UNFILLED GAPS 7741
DAILY STRUCTURE - BALANCE - 7897/7778 (7 DAY)
WEEKLY STRUCTURE - OTFH - 7778
MONTHLY STRUCTURE - OTFH - 7542
VIX BULL BEAR ZONE 17.7
VVIX-to-VIX ratio of 5.59 sits right in the historical "sweet spot" for market positioning, but its composition reveals a quiet shift in market dynamics
PRIMARY TRADES & TARGETS
LONG ON REJECT/RECLAIM OF THE DBBZ TARGET DAILY RANGE RES > ATH’S
***ADDITIONAL SETUPS & TARGETS HIGHLIGHTED ON THE CHARTS***
(I FADE TESTS OF 2 SIGMA LEVELS ESPECIALLY INTO THE FINAL HOUR OF THE NY CASH SESSION AS 90% OF THE TIME WHEN TESTED THE MARKET WILL CLOSE ABOVE OR BELOW THESE LEVELS)
SPX PUT/CALL RATIO 1.24 (The numbers reflect options traded during the current session.) A put-call ratio below 0.7 is generally considered bullish, and a put-call ratio above 1.0 is generally considered bearish.
JHEQX Upside cap (~7,920–7,950): Dealer gamma hedging at this call strike creates resistance, with market makers likely selling futures into strength and limiting volatility. Downside cushion (~7,270): If SPX drops 5% into Q4, long put gamma may force dealers to buy futures as the index falls, helping stabilize prices. Expiration: December 31, 2026. Strong pinning effects are likely near key strikes into year-end expiration.
DEC2025 OPEX to DEC2026 OPEX is 945 points giving us a range of [5889,7779]
Notes On Structure Implications
Balance: This refers to a market condition where prices move within a defined range, reflecting uncertainty as participants await further market-generated information. Our approach to balance includes favouring fade trades at the range extremes (highs/lows) while preparing for potential breakout scenarios if the balance shifts.
One-Time Framing Higher (OTFH): This represents a market trend where each successive bar forms a higher low, signalling a strong and consistent upward movement.
One-Time Framing Lower (OTFL): This describes a market trend where each successive bar forms a lower high, indicating a pronounced and steady downward movement.
JPM TRADING DESK VIEWS
JPMorgan Market Intel & Trading Desk Briefing — Day 1 Bank Earnings & Consumer Read-Through
Source Documents: JPMorgan US Market Intelligence, Trading Desk Commentary, & Positioning Intel
THE TAKE: RESILIENT US CONSUMER DOWNSIDE PROTECTION & DISCONNECT IN BANK PRICING
Day 1 of Q3 bank earnings provided a clear, consistent macro read-through: the US consumer remains resilient, anchored by low unemployment, expanding card spend, and improving credit metrics. Debit and credit card spend expanded significantly across reporting institutions—up +10% YoY at JPMorgan and +13% YoY at Citigroup—beating consensus expectations of a -100 bps deceleration. Early-stage delinquencies and net credit losses fell or stabilized YoY across Citi, Wells Fargo, and JPM.
Despite fundamental beats, major banks faced selling pressure into the print. Desk specialist Rob O'Dwyer notes this "head-scratching" price action is primarily driven by quantitative/systematic supply and 2s10s yield curve flattening anxieties. Because front-end yields (3m5y) remain virtually unchanged and net interest income (NII) trends remain strong into Q4, the desk views this weakness as a technical dislocation to fade and buy bank dips.
MACRO & CONSUMER HEALTH DASHBOARD (BANK READ-THROUGH)
Consumer Spend Trajectory: Chase internal spending data shows total September spending growth accelerating to +6.6% YoY (vs. 5.3% in August). Spend growth is broadly distributed across income cohorts: Upper (+7.8%), Middle (+8.2%), and Lower (+6.6%).
Income Cohort Stability: Lower-income household wage growth led all tiers in August at +4.7% YoY (vs. 3.8% Middle, 3.7% Higher), providing fundamental wage support against elevated fuel and living costs.
Payments Volume Beats: Visa (V +9.4% MTD) and Mastercard (MA +8.9% MTD) are riding strong consumer momentum into Q4. JPM card volume decelerated by only 40 bps, while WFC (+10 bps) and Citi (+60 bps to 13%) accelerated.
BANK EARNINGS SPECIFICS & NII OUTLOOK
Wells Fargo (WFC): Expects 4Q Net Interest Income (NII) to expand on fixed-rate asset repricing, strong deposit growth, and commercial & industrial (C&I) loan growth exceeding mid-single digits. Credit performance remains exceptional with early-stage delinquencies at historically low levels.
Citigroup (C): Reported low corporate non-accruals and net credit losses. Despite management conservatism around ROTCE targets, desk estimates point to full-year ROTCE trending closer to 12%.
JPMorgan Chase (JPM): Card net charge-off expectations held steady at ~3.2%, with solid loan growth supported by gas, travel, and core discretionary categories.
TRADING DESK FLOWS & MONETIZATION STRATEGY
TMT & AI Disruption Fears Fading: Fears over Meta's "Muse" agentic AI product disrupting e-commerce and internet search platforms are receding. Flow desk observed strong institutional demand for mega-cap quality / hyperscalers (META, MSFT, GOOGL, AMZN). Alphabet (GOOGL) confirmed 2027 capex will be materially higher, dispelling near-term spending deceleration fears.
Healthcare Outflows vs. Selective MedTech: Broad healthcare selling observed as hedge funds rotate back into TMT. Desk sees a tactical setup in beat-down MedTech (e.g., Boston Scientific BSX seeing generalist inflows) and distributors, while selling biotech (INCY, COGT).
Tactical Monetization Playbook:
Core Equities: Maintain a Tactically Bullish stance heading into the meat of earnings season. Semis (SOX ~15% below June ATHs) are poised to climb the wall of worry.
Consumer Reopening Theme: Focus on cruise lines, hotels, and select retailers (JP2RTL) which are insulated by resilient upper-income spending and offer attractive L/S positioning (37th percentile).
International Expressions: Prefer Brazil and Japan as non-US equity overweights.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!