Institutional FX Insights BofA ' USD & Equity Breadth'
BOFA GLOBAL RESEARCH FX & RATES STRATEGY BRIEFING: EQUITY BREADTH & THE US DOLLAR
THE TAKE: EQUITY BREADTH IS A STATISTICALLY SIGNIFICANT USD DRIVER
Bank of America Rates & Currencies Research demonstrates that US equity market breadth is a statistically significant, independent driver of the US Dollar Index (DXY), operating beyond traditional equity index levels and 2-Year Treasury yield differentials. Equity breadth serves as an empirical barometer of US Technology Exceptionalism vs. Global Growth Convergence:
Narrow Rally / Broad Sell-Off = USD Positive: When S&P 500 performance is concentrated in mega-cap technology while the broader market lags (i.e., S&P 500 equal-weighted
SPWunderperformsSPX), capital concentrates into US tech, supporting the Dollar.Broad Rally / Narrow Sell-Off = USD Negative: A broader market advance or a localized sell-off in mega-cap tech signals global growth convergence or an erosion of US AI exceptionalism, weighing on the Dollar.
October Market Read-Through: The stable-to-weaker USD during October’s equity drawdown aligns with AI debt and capex concerns undermining the US exceptionalism narrative.
REGRESSION BETA BREAKDOWN & SCENARIO ANALYSIS
BofA strategists regressed weekly FX returns since 2015 against the relative performance of equal-weighted S&P 500 (SPW) vs. cap-weighted S&P 500 (SPX), controlling for 2-Year US Treasury rates and S&P 500 index moves:
DXY Sensitivity: A 1% rise in
SPWvs.SPX(improving breadth) is associated with a -0.2% depreciation in the DXY Dollar Index.Cyclical FX High Betas: The most cyclical, high-beta currencies—specifically the Nordics (SEK, NOK) and Antipodeans (AUD, NZD)—display the highest statistical sensitivity to equity breadth, reinforcing the global growth read-through.
EUR/USD Breadth Sensitivity: For EUR/USD, the equity breadth sensitivity exceeds standard equity level sensitivity, making
SPW/SPXperformance a critical input for Euro positioning.Japanese Yen (JPY) Exception: JPY is the sole currency outlier where the equity breadth beta is not statistically significant. Japan's foreign asset structure (skewed toward FDI rather than portfolio flows) means front-end US yields—rather than equity risk sentiment—dominate USD/JPY directional moves.
ILLUSTRATIVE MARKET SCENARIOS
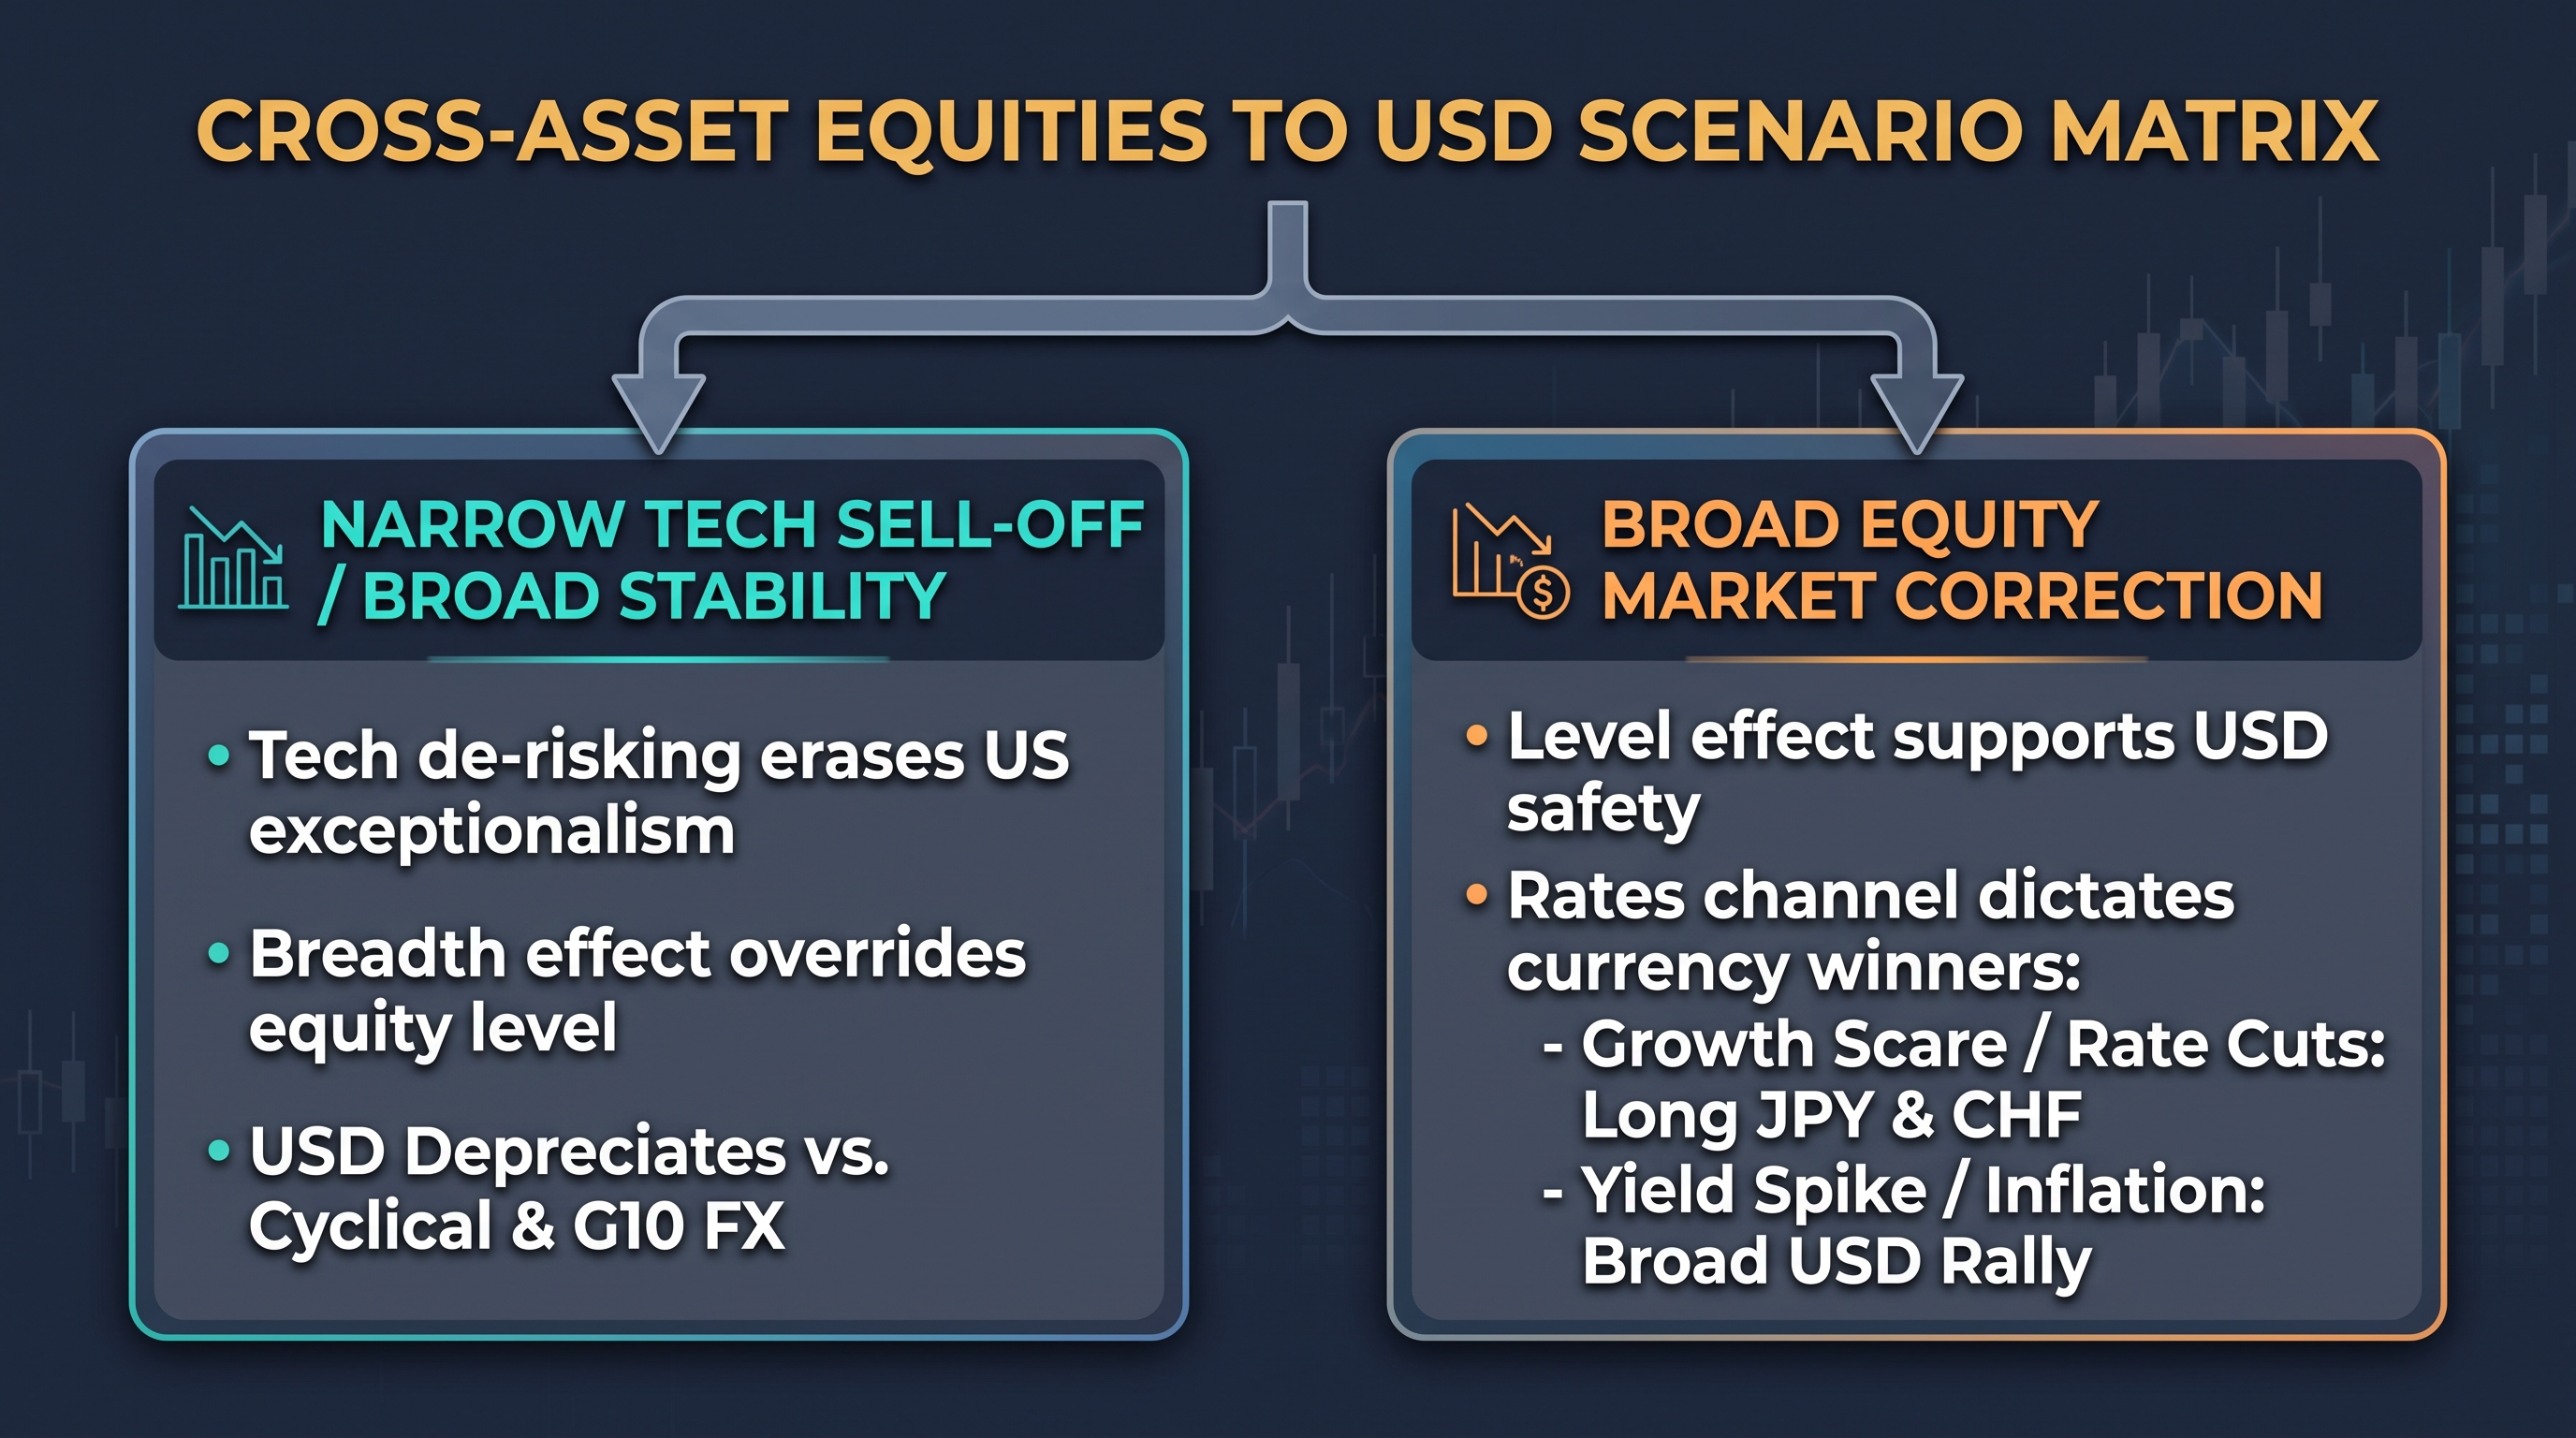
Broadening Rally Scenario: Both equity level and breadth effects act in tandem to depress the USD, driving strong outperformance in high-beta and cyclical currencies.
Tech-Led Equity Correction (10% SPX Drop with 6% SPW Outperformance): The positive USD impact from falling equity index levels is neutralized by the negative USD impact of improving relative breadth (
SPW > SPX). DXY remains broadly net-neutral.Rates Channel Dominance in Equity Pullbacks:
Driven by US Growth Scares / Lower Front-End Yields: Favors long JPY and CHF positions over USD.
Driven by Higher Treasury Yields (2022 Style): Broadly USD positive across the board.
Source Document: BofA Global Research (Adarsh Sinha, Oliver Levingston)
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!