FTSE Extends Rally as Banking Gains and Lower Yields Offset Oil Volatility
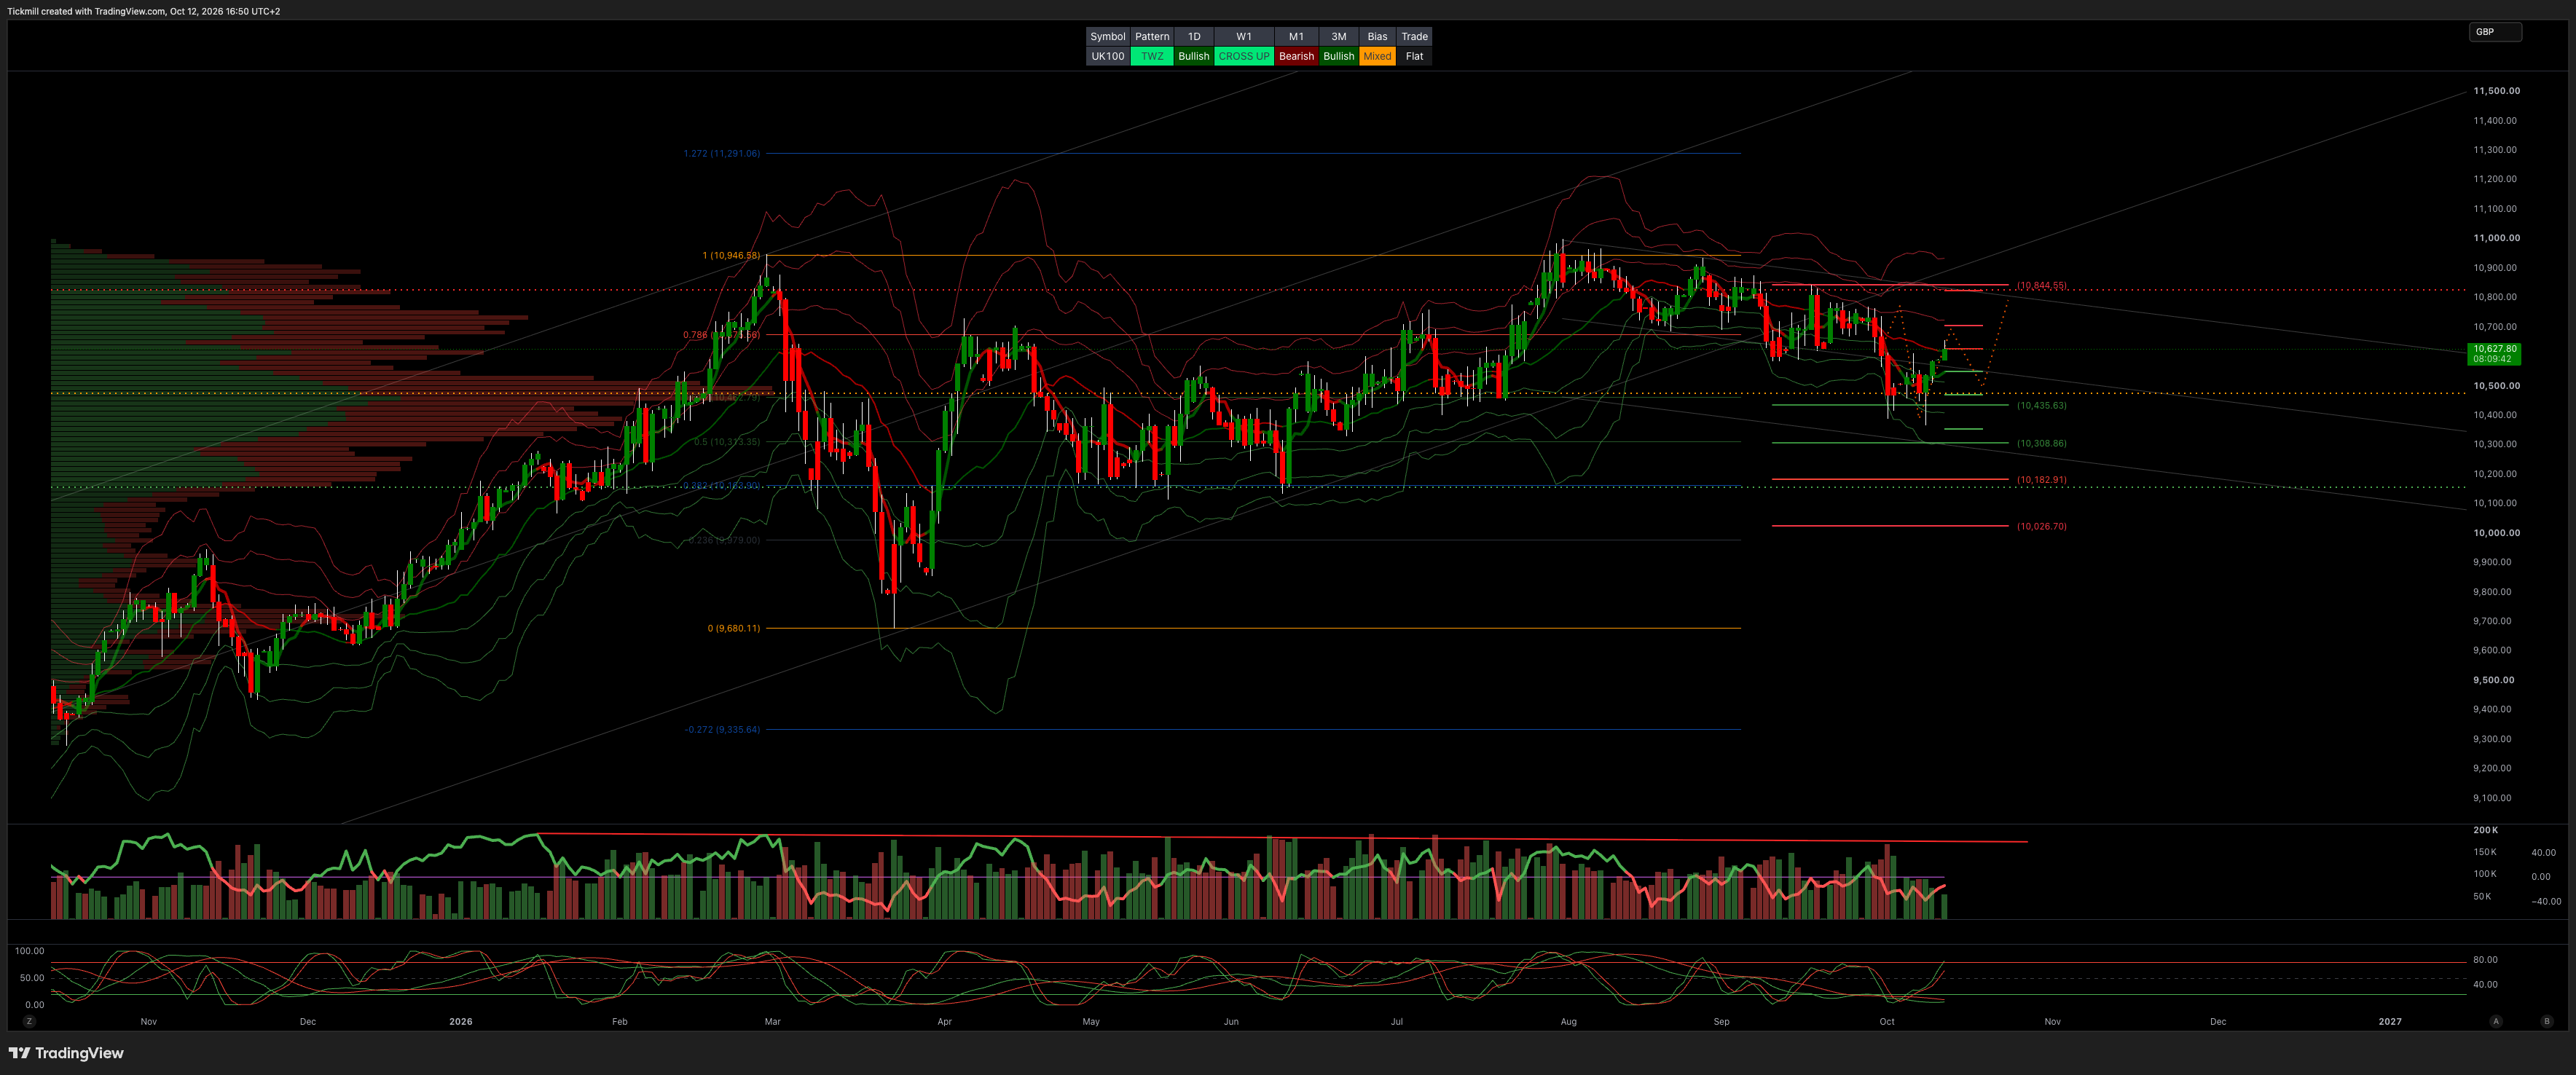
FTSE Extends Rally as Banking Gains and Lower Yields Offset Oil Volatility
London's benchmark FTSE 100 extended its upward momentum on Monday. Investors drew confidence from declining gilt yields and steady buying across financial and defensive growth sectors, building on Friday's relief bounce as market sentiment continued to stabilise.
Heavyweight banking and financial stocks spearheaded top-flight gains. HSBC Holdings advanced over 2%, supported by reports of a pivot toward performance-based bonus structures, while Standard Chartered moved up 1.8% and Barclays added 1.6%. Lloyds Banking Group and NatWest Group gained 1.5% and 1.4%, respectively. Healthcare specialist ConvaTec Group climbed nearly 4% to lead individual risers, while Lion Finance surged 3.1%. Broad-based buying across defence, financial services, and media lifted Computacenter, Standard Life, BAE Systems, London Stock Exchange Group (LSEG), Admiral Group, Babcock International, Legal & General, Reckitt Benckiser, Games Workshop, The Sage Group, AutoTrader Group, IAG, and RELX by between 1.2% and 2.0%. Pearson, M&G, Smith & Nephew, Aviva, Hiscox, Smiths Group, and Rentokil Initial also logged solid upside.
Conversely, recruitment and advertising names faced isolated selling pressure. Shares of recruiter Hays Plc tanked 8% after reporting a 3% drop in first-quarter like-for-like net fees, hitting its lowest level since August. Media group Informa dropped about 2.5%, while WPP, Vodafone Group, InterContinental Hotels Group, 3i Group, Barratt Redrow, and Next drifted lower between 0.5% and 1.1%.
Commodity and fixed income markets reflected competing global dynamics. Front-month Brent crude futures exhibited intraday volatility, dipping to $102.33 a barrel before recovering to trade up nearly 1% around $105.74 a barrel as traders weighed reports of potential Russian energy ceasefire discussions against ongoing Middle Eastern security risks. Meanwhile, fixed income markets analysed structural dislocations, noting that the Bank of England's implicit reaction function to Federal Reserve tightening remains difficult to justify under plausible macro scenarios. With Gilts implying significant policy tightening ahead of a likely November rate hike, a resilient Sterling would allow the MPC to avoid importing FOMC tightness, whereas currency weakness could force a more hawkish stance despite diminishing marginal exchange-rate support from higher domestic yields.
The UK calendar is lighter, with BRC retail sales Tuesday and production, trade and GDP data Thursday. Q3 began with a 0.4% m/m GDP gain, leaving quarterly tracking near 0.6%. Survey data suggest expansion extended into August, and a 0.2% m/m gain would keep UK growth looking more resilient than expected. That resilience still masks household stress. The BoE’s Q3 credit conditions survey showed overall defaults remain low, but unsecured lending is under pressure. Demand for credit cards and unsecured loans continues to rise, while default rates are also moving higher. With the Ofgem price cap set to reset higher over winter, households reliant on revolving credit face a tougher mix of inflation, rates and taxes.
Finish Line: U.K. equities maintained a positive posture as strong bank earnings expectations and easing fixed-income yields drove a broad-based rally. While recruitment updates and crude oil swings provided localised friction, the FTSE 100 relies on momentum in financial and defensive heavyweights as markets navigate cross-currents between central bank policy paths and global energy supply risks.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!